Coal still present in ports. Europe increased imports from Russia in 2025
 By
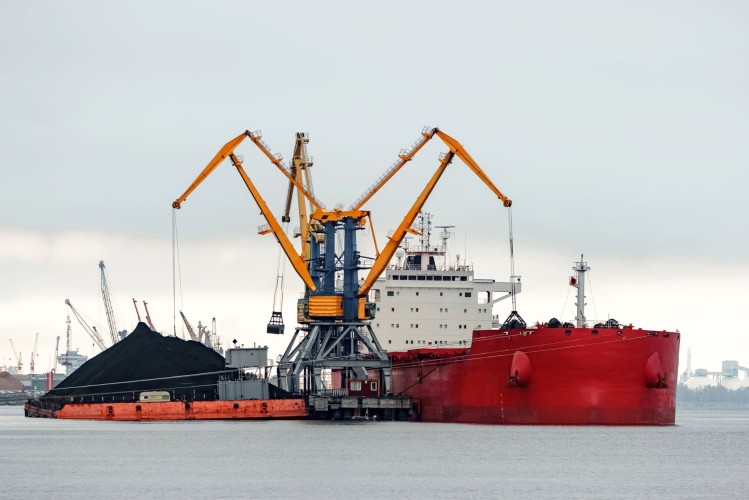
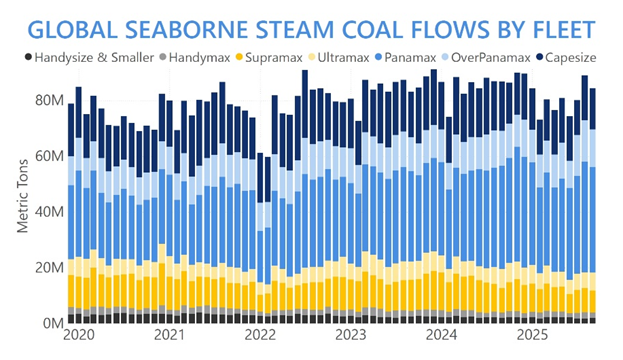
Coal piles are still visible in some European bulk terminals and warehouses. Congestion, terminal congestion, and coal-laden ship queues are a thing of the past in Europe. In 2025, global seaborne coal transport fell by 2.8% year-on-year to 1,333.1 million tons (excluding cabotage), according to ship tracking data from AXS Marine. Loading ports and conveyor belts at import ports operated at a slower pace than a year earlier, according to analysis by Banchero Costa Research.
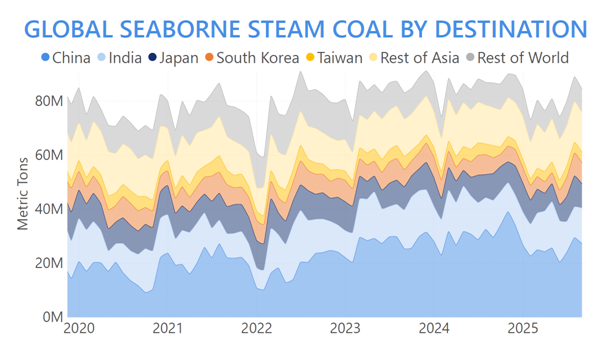
The market is driving demand for thermal coal. Global demand for thermal coal will continue to fluctuate in 2025. Asia is ahead, Africa is slowly growing, and Europe remains within a narrower (but still noticeable) range, AXS Marine experts note. In their opinion, “thermal coal transport is characterized by seasonal stability – unlike wheat or nickel, which fluctuate rapidly with harvests or price shocks.”
The only fluctuation in maritime transport was observed in February, which is attributed to a shorter period of activity for fleets and bulk terminals and a slowdown in the PRC economy related to the Chinese New Year.
In 2025, Indonesia’s exports fell by 6.9% year-on-year to 496.1 million tons, and Australian open-pit mines reduced supplies to the international market by 0.4% year-on-year to 354.6 million tons, according to Banchero Costa Research. Meanwhile, coal exports from Russia increased by 6.5% year-on-year to 172.6 million tons, offsetting a decline in coal supplies from the US. Americans experienced a 10.6% year-on-year decline in coal demand and loaded 81 million tons of coal onto ships.
During this time, South African mines replenished the market, and loadings at South African ports increased by 3.8% year-on-year to 64.5 million tons. Supplies from Colombia fell significantly, by a staggering 14.9% year-on-year to 47.6 million tons. Canadian ports also loaded 2.7% less coal than in 2024, reaching only 47.9 million tons. Mozambique saw a 2.7% year-on-year decrease in coal shipments (20.7 million tons).
 Suurce: AXS Marine
Coal Leaders – China, India, and Japan
The economies of China, India, and Japan have been shaping the import market for years. Market fluctuations play a significant role in price movements and supply flows along trade routes. Seaborne coal imports to mainland China fell by 11.1% year-on-year to 379.7 million tons around 2025. India’s imports decreased by 5.6% year-on-year to 223.2 million tons, and those to Japan fell by 3.6% year-on-year to 151.5 million tons. Between January and December 2025, the South Korean economy reduced coal demand by 3.2% year-on-year to 106.7 million tons. Imports to Vietnam also decreased by 0.2% year-on-year to 56.4 million tons. Taiwan’s small economy also reduced coal imports (by 5.7% year-on-year) to 52.7 million tons.
All EU countries collectively import over 10 million tons more coal than Taiwan. Yet, in the January-December 2025 period, EU coal imports fell by 1.4% year-on-year to 63.7 million tons. The Turkish economy also reduced demand by 4.5% year-on-year to 36.2 million tons. As a result of changes in global markets and the energy transition, the European Union is now the fifth-largest importer of seaborne coal, notes Banchero Costa Research.
According to “Coal 2025: Analysis and forecast to 2030,” the latest report by the U.S. International Energy Agency (EIA), EU countries have been reducing coal imports since 2022 and seeking to reduce their reliance on external suppliers. The supplier market is impacted by declining sales revenues due to falling coal prices. The maritime transport market is significantly impacted by the decline in coal freight.
The EIA notes in the report: “After record increases in thermal coal prices during the recent energy crisis related to Russia’s invasion of Ukraine in 2022, prices have declined over the past two years. In 2025, prices were about 10% lower in Europe and about 20% lower in Asia compared to 2024, although there were significant geographic differences throughout the year.”

European Union – 30 million tons down
In 2024, the EU had only a 4.7% share of global seaborne coal supplies, compared to 9.9% in 2022. Seaborne coal imports to the EU increased by 23.3% year-on-year in 2020-2021 to 92.3 million tons, and then by 38.2% year-on-year in 2022 to 127.6 million tons. Banchero Costa suggests that this was due to “lower gas imports from Russia.” However, in 2023, EU imports fell sharply by 30.4% year-on-year to 88.8 million tons, and then by a further 27.2% year-on-year in 2024 to 64.6 million tons.
Leading European importers returned to shifting their energy import mix to LNG two years ago. Coal, as the only energy resource imported from Russia, has been replaced by gas, also imported from Russia. In some countries, the development of renewable energy is impacting the volume of energy resource imports by sea. Previously, in 2020, we observed a 32.9% year-on-year decline in European coal imports, 18.3% year-on-year in 2019, and 7.6% in 2018.
In 2025, the situation stabilized, with import terminals unloading 63.7 million tons. This represents a slight decline of 1.4% year-on-year, but is 50% less than the coal supply in 2022. Just a few years ago, Europe was heavily dependent on Russia for supplies. After 2023, this situation changed drastically.
 Source: U.S. International Energy Agency (EIA)
US miners have pushed Russia out of the EU
In 2021, as much as 44% of EU seaborne coal imports came from Russian ports. In 2025, following Russia’s attack on Ukraine, the share of Russian coal in EU imports fell to 9.5%. This figure also includes Kazakh coal transported through Russian ports. However, it should be noted that in the January-December 2025 period, EU coal imports from Russian ports unexpectedly increased by 64.5% year-on-year to 6.1 million tons, while in 2024, European ports received 3.7 million tons of coal imported by sea from Russia.
However, this is still 80% less than the 38.3 million tonnes delivered to EU countries in the January-December 2021 period. The United States was the most important supplier of coal to Europe in 2025. The main beneficiaries of changes in the EU’s import structure were US miners, which accounted for 28.5% of European imports. In 2025, bulk carriers brought 1.2% more coal by sea from the US to the EU, but this was only 18.2 million tonnes. These were still significantly lower deliveries than in 2023 (24.2 million tonnes in the January-November 2023 period).
Source: axsmarine.com
The second largest supplier to Europe is Australia, whose coal ports accounted for 23.2% of EU imports in 2025. However, in 2025, imports from Australia to the EU fell by a staggering 15.9% year-on-year to 14.8 million tonnes. Colombia ranked third among coal suppliers, with a 14.5% share in 2025. In 2025, ships from Colombia to the EU delivered 1.6% more coal year-on-year (9.2 million tonnes) to European bulk terminals. This was significantly less than the 14.8 million tons recorded in the January-December 2023 period.
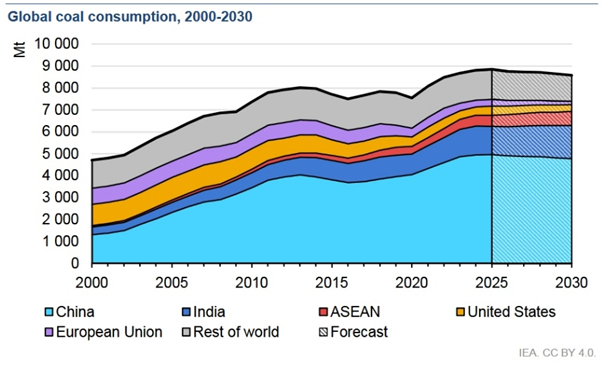
The EIA’s prediction that global coal demand would reach 8,845 Mt in 2025 proved accurate, setting a new record. The increase of approximately 40 Mt compared to 2024 is very close to the forecast we presented last year. The United States recorded the largest absolute increase, approximately 37 Mt, supported by policy measures and higher gas prices. In the European Union (EU), the decline in coal demand continued. This means that coal carrier and bulk terminal operators cannot count on a high coal supply. EU countries’ demand for coal is falling, primarily for seaborne imports.