The Chinese Year of the Fire Horse and the rapid changes in the container shipping market, ports and shipyards
 By
The Year of the Fire Horse for operators began with electrifying news of further market consolidation through Hapag-Lloyd’s acquisition of ZIM for $4.2 billion. More important, however, is the fact that mergers and acquisitions and the monopolization of the container market have not impacted freight growth in 2026 and likely will not in 2027. The Fire Horse may herald a time of rapid changes in shipping routes, galloping energy in seaports and shipyards, and unpredictable shifts in maritime transport markets.

Container freight has fallen for a fifth week following weaker-than-expected growth in shipments before the Chinese Lunar New Year. Spot rates on the trans-Pacific and Asia-Europe routes reached record lows. As a result, the Freightos Baltic Index (FBX) fell to $1,927 per FEU from around $2,500/FEU in early January. Liner operators defended themselves by withdrawing approximately 125 sailings in the coming weeks.
The charter market failed to respond to the emergence of a new, strong operator and continued to behave as it did in 2025. In the second week of February 2026, several operators secured quite favorable charter contracts, with prices in line with other recently concluded contracts. However, the exceptionally low tonnage supply is undoubtedly a key factor in helping shipowners effectively manage two- and three-year charters, according to analysts at MB Shipbrokers.

Slow Charters
Another week has passed without any confirmed charter contracts in the Post-Panamax segment. Yet, there is still a shortage of approximately 10% to 15% of cargo space due to the need to extend sea lanes around Africa. Demand for container transport on sea lanes is driven by reduced container ship traffic through the Red Sea and the Suez Canal. Despite this, BIMCO predicts a balance between supply and demand growth in 2026.
After the two-week shutdown in China, cargo space supply is forecast to increase by 3%, and demand by 2.5-3.5%. Supply growth is also estimated to slightly outpace demand growth in 2027. Next year, supply growth could exceed 2026 by 3.5%, and demand for maritime container transport will increase by 2.5-3.5%. BIMCO predicts that the supply-demand balance in 2027 will be weaker than in 2025, but in 2026 it will remain close to the 2025 level.
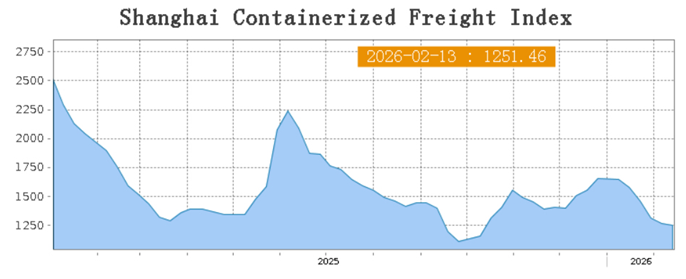
SCF Index. Source: Shanghai Shipping Exchange
The return of the Suez Canal to the mainland will be unfavorable for shipowners, but favorable for shippers. This could reduce demand for container ships by 10%. If sailing speeds don’t decline as forecast, supply could grow faster by 1.2% annually, according to BIMCO analysts. Negotiations for two- and three-year charters are ongoing, but operators are awaiting more detailed information on new ship deliveries from shipyards.
The decline in activity on liner services was likely caused by the continued growth of global container cargo volumes in 2025. This was noticeable at container terminals, which are reporting significant increases in transshipment in most markets, except for the US. Initial analyses of activity on liner services indicate that their throughput in 2025 increased by 4.7% year-on-year.

Galloping into 2025
December ended the year with an exceptional result of 16.97 million TEU, surpassing the previous monthly peak recorded in August and achieving a 4.7% increase compared to December 2024, according to analysts at MB Shipbrokers. They report that “In absolute terms, monthly container volumes exceeded 16 million TEU for eight of the twelve months of 2025.” These figures were reached only three times in 2024, and in 2025, such a supply of containers on ships became the new norm.
The market was primarily driven by the economies of Southeast Asia and India. Here, container turnover volumes increased by 11.6% and 5.9%, respectively, in 2025 compared to the entire year 2024. On the supply side, China holds a secure position. This economy ensured a 5.6% year-on-year increase in container exports.
Cumulative global container volume reached 192.9 million TEU in 2025, according to data from Container Trades Statistics Ltd (CTS). This compares to 184.3 million TEU in 2024. This demonstrates that the economies of major markets have withstood President Donald Trump’s tariff wars.
Non-tariff measures have not hindered trade either. Liner operators have also found ways to circumvent major threats on maritime routes and stabilized connections around Africa. This demonstrates the sector’s resilience despite ongoing geopolitical and macroeconomic uncertainty.

Shipyards in full gallop
A record order book and record container ship deliveries in 2026-2027 will ensure that freight will ensure profitability for liner fleets in the Horse Year. New contracts from COSCO and Hapag-Lloyd, placed in December 2020,5 increased the total number of container ships ordered in 2025 to a record 633 vessels. Ships with a total capacity of over 5 million TEU will be built in the docks, according to Linerlytica data. In December of last year, the previous record of 4.74 million in 2021 and 4.77 million in 2024 were exceeded. Chinese shipyards contracted a staggering 72% of last year’s orders in TEU terms.
In 2026, the primary market saw a small but significant increase. Contract activity intensified in February. Maersk has announced a contract for eight 18,600 TEU vessels with LNG systems. The Danish operator will execute the order at New Times Shipbuilding. The vessels will enter service in 2029 and 2030. This increases Maersk’s order book at New Times to 22 vessels.
Mitsui/Nissen has placed an order with Samsung for two 13,000 TEU vessels, with delivery scheduled for May 2028. The price was estimated at approximately USD 161 million per vessel. It is assumed that this order was placed with the prospect of an already agreed charter. Venergy of Greece has announced orders for two 1,930 TEU vessels, which have been placed at CSSC Huangpu Wenchong. The vessels have been contracted for USD 34 million each. The container ships will be delivered in 2029.
The Lunar New Year will temporarily slow down the container market in shipping, ports, and shipyards. But from the end of February, the Year of the Fire Horse will gallop off. It could also be a time of rapid changes in shipping routes, galloping energy in shipyards, and unpredictable shifts in maritime transport markets.
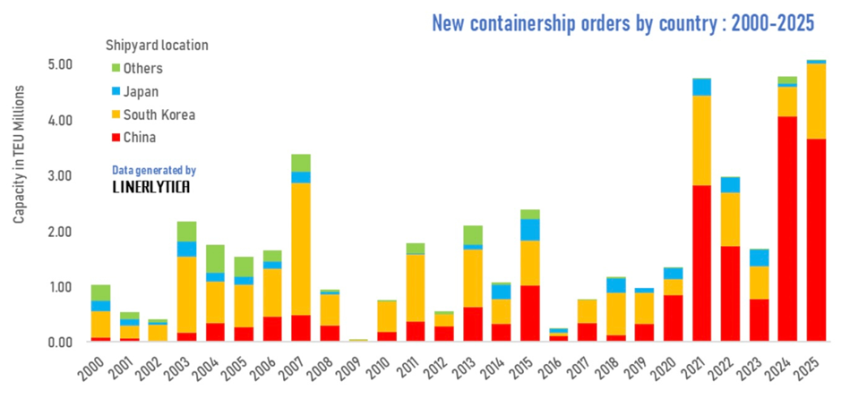
Source: Linerlityka