Logistical bypasses in the Strait of Hormuz. Shipowners, logisticians, and terminal operators have built alternative logistics channels [ANALYSIS]
 Source CMA CGM

In response to the blockade of the Strait of Hormuz, leading shipping companies have found ways to at least partially relocate cargo between Arabian Peninsula ports and international markets. Container and bulk carrier owners, freight forwarders, and terminal operators have taken such action. Bypasses and alternative routes on the Arabian Peninsula and its surroundings must develop into a sustainable logistics network.
The dependence of Persian Gulf countries on imported goods on the one hand, and the markets’ dependence on oil, gas, and refined products on the other, have created a need to streamline logistics. Major liner operators, including MSC, Maersk, and CMA CGM, along with logistics providers, have developed new transport routes that allow for bypassing the uncertain passage through the Strait of Hormuz.
All container ship operators have established new routes from Red Sea and Gulf of Oman ports, including Yanbu and King Abdullah Port in Saudi Arabia, as well as Fujairah in the United Arab Emirates, to ports such as Dammam in Saudi Arabia, Basra in Iraq, and Jabal Ali in the United Arab Emirates, the region’s largest transport hub. However, the freight transport problem is not limited to unitized cargo.
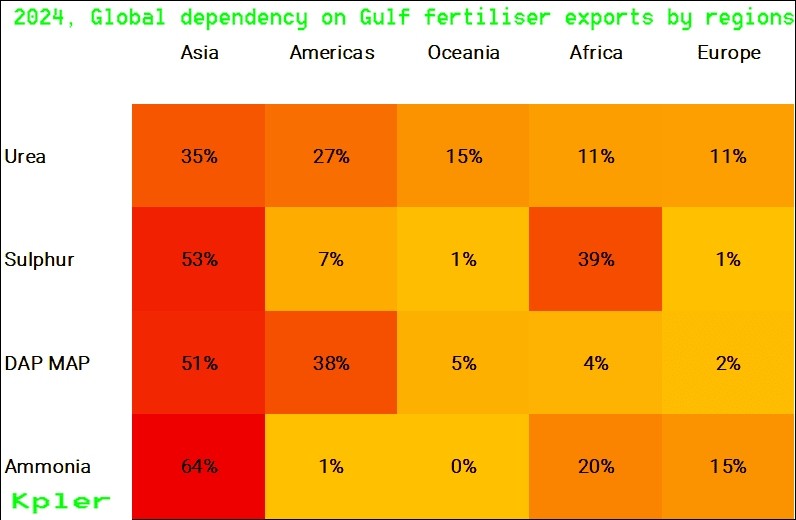
2024, Global Dependence on Fertilizer Exports from the Persian Gulf by Region. Source: Kpler
Strategic Fertilizers
About 33% of the world’s fertilizers, including sulfur and ammonia, pass through the 21-mile-wide Strait of Hormuz, which separates Oman’s Musandam Peninsula from Iran. Disruptions in shipping traffic have significantly restricted trade in chemical products. According to Kpler data, 1.5 million tons of fertilizers have been traded in the region so far in June, notes Swati Kushwaha on the blog https://www.kpler.com/blog/.
US missile attacks on Iran have already led Iranian fertilizer producers to halt urea and ammonia production. Egyptian production plants have ground to a halt due to disruptions in gas supplies from Israel. Gas supplies to Jordan have decreased. Urea prices have risen in the US, Brazil, and the Middle East. Saudi Arabia raised urea prices to $450/ton FOB, significantly above $402/ton FOB. CFR urea prices in Brazil also rose by $32/ton, according to Kushwaha.
Kpler data indicates that, as a result of the Strait of Hormuz obstruction, sulfur and urea supplies will decline by 44% and 30% annually in 2026. Monthly deliveries from the region have so far ranged from 3 to 3.9 million tons of fertilizers. Sulfur accounted for approximately 1.5 to 1.8 million tons of international supply. Urea (1.2 to 1.5 million tons), ammonia (approximately 400,000 tons), and phosphates (up to 500,000 tons) were also exported from chemical plants located on the Persian Gulf. Pipeline networks can only transport crude oil or gas.
The United States, which attacked Iran, appears to be more vulnerable to fertilizer supply disruptions than anticipated before the war and the blockade of the Strait of Hormuz. In 2025, the Gulf states accounted for 48% of U.S. imports of nitrogen fertilizers [HS3102] and 60% of potash fertilizers [HS3104]. In the first five months of 2026, shipments of these commodities fell by 31% and 56%, respectively, according to Descartes Datamyne.
The Gulf states, led by Qatar, also accounted for approximately 14% of all U.S. imports of nitrogen fertilizers [HS3102] and 30% of urea [HS310210], a key fertilizer raw material. Census data analyzed by Descartes Datamyne show that in 2025, Qatar accounted for 12% of nitrogen fertilizer imports and 22% of urea imports. The Fertilizer Institute estimates that the United States imports about 36% of its urea, up from 58% in 2014.
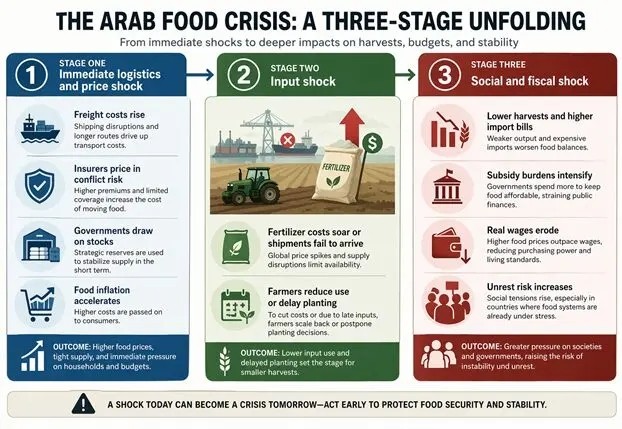
Stages of transition to a food crisis in Arab countries. Source: Center for Environment and Development for the Arab Region and Europe (CEDARE)
New Port will bypass Hormuz
News agencies report that DP World is the furthest in its plans to create new corridors. The global container terminal operator is reportedly planning to build a new port and container terminal on the east coast of the United Arab Emirates. The management board of DP World, based in Dubai, is reportedly already in talks about a new multi-purpose port in the seaside district of Fujairah. A container terminal is also to be built here, it was reported on the cover page of the Financial Times (July 14, 2026).
Currently, only a few ships a day can pass through this waterway, compared with more than 130 crossings a day before the war. Clearing the Hormuz crossing will not balance supply and demand in the near future. Bypasses and alternative routes in and around the Arabian Peninsula must develop into a sustainable logistics network.
Logistics operators give priority to groups of essential goods, such as food and medicines. Tata Group said tea, salt and pulses destined for the Middle East are currently being transported to ports such as Jeddah in Saudi Arabia and Khor Fakkan in the United Arab Emirates. They are then transported to recipients by truck.
Imported grain shipments also reach the market through the ports of the Red Sea and the Gulf of Oman. From the unloading terminals, they are transported further by trucks and smaller ships. As Ukrinform reported earlier, the United Arab Emirates plans to accelerate the construction of a new oil pipeline to double export capacity through Fujairah by 2027, significantly increasing export opportunities and bypassing the Strait of Hormuz.
However, the construction of pipelines will not ensure food stability on markets dependent on the permeability of Persian Gulf ports. However, CEDARE analysts assume that a domino effect has already occurred. The Center for Environment and Development for the Arab Region and Europe (CEDARE) concludes that “The growing food crisis resulting from the war with Iran should be understood as a complex systemic shock.”
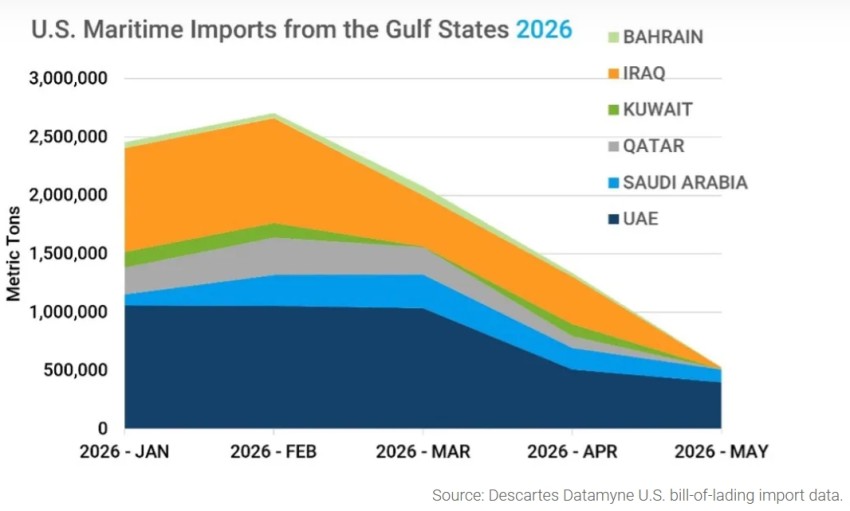
US Imports from the Persian Gulf Countries in 2026. Source: Descartes Datamyne
Regional War: Global Consequences
Regional wars cause spikes in energy prices, which impact the production of fertilizers and agricultural inputs. As a result, we experience disruptions in food production and supplies. These factors lead to tensions in financial markets and regional instability. CEDARE emphasizes: “Arab countries are among the most vulnerable [to economic and social tensions – MG], as many of them are heavily dependent on imported food while simultaneously struggling with water shortages, climate stress, and, in many cases, active conflicts.”
Local disruptions in the Strait of Hormuz are having a significant impact on global markets. The United States has also been affected. Data compiled by Descartes Datamyne, based on the analysis of bills of lading, indicates that the volume of cargo from the Persian Gulf states (excluding Iran) arriving at US ports fell by 32% in the first five months of 2026 compared to the same period in 2025. In May alone, imports from these sources fell by 67% year-on-year.
The construction of alternative routes bypassing the Strait of Hormuz has become a reality and will transform into a real process of investing in new ports and land connections, including pipelines. The rapid development of bypasses to Arab countries presents an opportunity not only for the Arabian Peninsula and its neighbors. It is also a chance to stabilize supplies to economies dependent on trade with this region, including the United States.
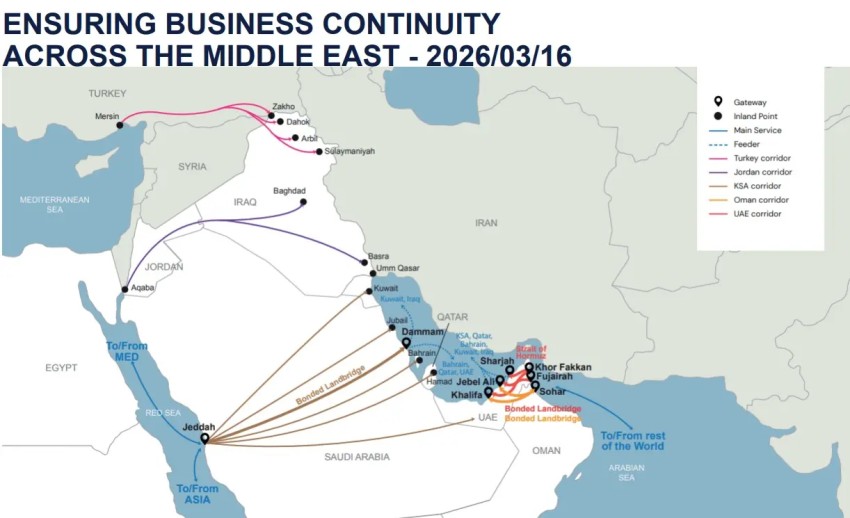
CMA CGM Logistics Bypass. Source: CMA CGM